
When Do You Need to Register for VAT?
Understand the UK VAT registration threshold, the rolling 12-month test and what to do as your business approaches it.
AI-assisted official-source check · 7 September 2026 — Effective registration date after exceeding the rolling threshold.
In brief
A UK business normally needs to register when VAT-taxable turnover exceeds £90,000 in a rolling 12-month period, or when it expects to exceed £90,000 in the next 30 days alone. The test is based on taxable turnover, not profit or a fixed accounting year.
The compulsory registration threshold
A UK business must normally register for VAT when its VAT-taxable turnover for the previous rolling 12 months exceeds £90,000. This is a rolling test, not a test based only on the tax year, calendar year or company year.
Check the total at the end of every month. If the rolling taxable turnover goes above the threshold, the business normally has 30 days from the end of that month to tell HMRC, and the effective registration date is usually the first day of the second month after the month the threshold was exceeded. For example, exceeding it in July normally gives an effective date of 1 September.
The next-30-days test
A separate forward-looking rule can apply if the business expects taxable turnover to exceed £90,000 in the next 30 days alone. A large new contract or order can therefore trigger registration without waiting for the historic rolling total.
What counts as taxable turnover
Taxable turnover generally includes supplies that would be standard-rated, reduced-rated or zero-rated if the business were registered. Exempt income and income outside the scope of VAT are treated differently. Zero-rated sales can still count toward the registration threshold.
The classification of income can be technical. Businesses near the threshold should confirm which sales count rather than relying on a software category name.
Voluntary registration
A business can register before it is required to. Voluntary registration can help where customers are VAT-registered and can reclaim VAT, or where the business has significant input VAT on costs. It may be commercially less attractive where customers cannot reclaim VAT and the business cannot increase prices.
Registration also creates record-keeping, invoicing, return and payment responsibilities, including Making Tax Digital for VAT for most registered businesses.
What changes after registration
- Apply VAT correctly from the effective registration date.
- Issue valid VAT invoices and display the VAT number.
- Keep the required digital VAT records.
- Submit VAT returns and pay amounts due on time.
- Reclaim input VAT only where the rules and evidence allow it.
- Review contracts and prices so the VAT cost is understood.
Common mistakes
- Checking turnover only once a year.
- Monitoring profit instead of taxable sales.
- Excluding zero-rated sales from the threshold without checking.
- Charging VAT before registration or mishandling the effective date.
- Registering voluntarily without reviewing customer pricing.
- Waiting for the accountant to notice the threshold after it has been crossed.
Monthly VAT threshold check
- Calculate VAT-taxable turnover for the latest rolling 12 months.
- Identify expected large sales in the next 30 days.
- Check the VAT liability of unusual income.
- Review pricing and customer impact.
- Make sure your system can produce digital VAT records.
- Register or seek advice promptly when a test is met.
Common questions
Do sole traders need to register for VAT?
Yes, when the VAT registration rules apply. The tests can affect sole traders, limited companies and partnerships.
Is the VAT threshold based on profit?
No. It is based on VAT-taxable turnover, which is a measure of relevant sales.
Can I register before reaching the threshold?
Yes. Voluntary registration is possible, but the pricing, customer and administrative effects should be reviewed first.
Do zero-rated sales count toward the threshold?
They can. Zero-rated supplies are taxable supplies, while exempt and outside-the-scope income are treated differently.
Related guidance
Continue with another useful guide from this topic.
VAT & Making Tax Digital
What Is VAT in the UK?
A plain-English guide to VAT, VAT rates, taxable turnover and what VAT registration means for small businesses.
VAT & Making Tax Digital
Should You Register for VAT Voluntarily?
Understand when voluntary VAT registration may help, when it may hurt and what to check before applying.
VAT & Making Tax Digital
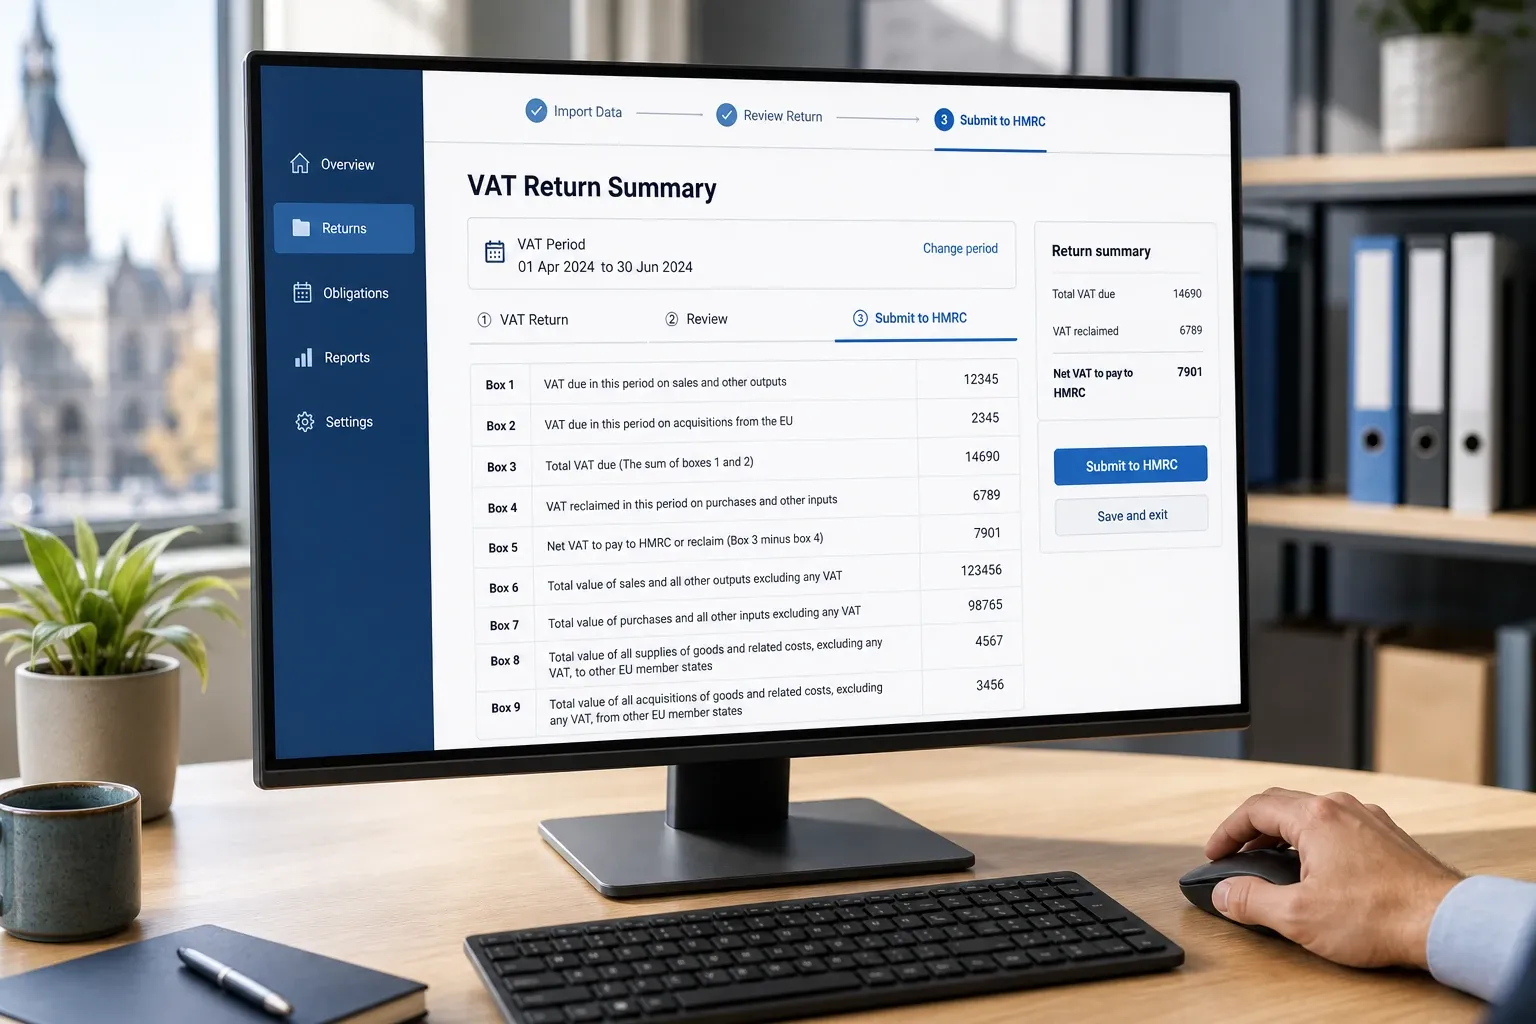
What Is Making Tax Digital?
A practical introduction to HMRC's digital tax rules for VAT, Income Tax and business record keeping.
VAT & Making Tax Digital
Who Needs to Use Making Tax Digital for Income Tax?
Understand the MTD for Income Tax thresholds, qualifying income and what sole traders and landlords should prepare for.
Need tailored support?
Talk through your position with Sparks
Bring your questions and records to a free consultation. We will explain the next steps in clear, practical terms.