
Construction Industry Scheme (CIS): a guide for subcontractors and contractors
Understand CIS registration, 20% and 30% deductions, gross payment status, records and Self Assessment reporting.
In brief
CIS affects many construction contractors and subcontractors. Contractors verify workers, apply the rate HMRC gives them and pay deductions to HMRC; subcontractors need to keep every payment statement and report their full income correctly at year end.
What the Construction Industry Scheme is
The Construction Industry Scheme (CIS) is an HMRC scheme for construction work carried out by subcontractors rather than employees. A contractor usually verifies a subcontractor, deducts an amount from the labour element of the payment and pays that deduction to HMRC as an advance payment towards the subcontractor's tax and National Insurance.
Receiving a payment statement that looks similar to a payslip does not automatically make someone an employee. Employment status must be considered separately; a genuine subcontractor does not automatically receive employee rights such as paid holiday or Statutory Sick Pay.
Work that can fall within CIS
CIS covers a wide range of construction operations, including building, extensions, alterations, demolition, site preparation, repairs, decorating, electrical work, heating and water installation, and some site-related traffic-management work.
Work done directly for a homeowner, rather than for a contractor, is often outside CIS. The facts matter, especially where a business is both a contractor and a subcontractor on different jobs.
Registering and the roles involved
A contractor engaging subcontractors for construction work generally needs to register, verify each subcontractor, apply the rate HMRC gives them, submit monthly CIS returns and pay deductions to HMRC.
A subcontractor can register for CIS. Registering usually means the standard deduction rate of 20% can apply once HMRC has verified the details. If the subcontractor is unregistered, cannot be verified or provides incorrect details, the higher 30% rate can apply. A subcontractor with gross payment status is paid without CIS deductions, but remains responsible for their tax bill.
What is deducted
CIS is normally calculated from the labour element. Amounts for VAT, materials paid for directly by the subcontractor, qualifying consumable stores and plant hired for the job are not normally subject to the deduction when they are properly evidenced and shown separately.
If your industry uses self-billing, the contractor produces the payment document instead of you issuing a conventional invoice. Check the days worked, rate, materials and deduction every time before treating it as correct.
A simple deduction example
Two subcontractors each charge for 20 days at £200 per day, so the labour amount is £4,000. One of them also has £200 of separately evidenced materials.
- An unregistered subcontractor at 30%: £4,000 labour less a £1,200 CIS deduction leaves £2,800.
- A registered subcontractor at 20%: £4,000 labour less an £800 CIS deduction, plus £200 materials, leaves £3,400.
The deduction is an advance payment, not the final tax calculation. At the end of the tax year, the full invoiced income, allowable expenses and CIS deductions need to be considered together.
Gross payment status
Gross payment status lets a qualifying subcontractor receive payment without CIS deductions. HMRC assesses whether the relevant business, turnover and compliance conditions are met. In practice, timely returns, tax payments and good records matter, so it should be applied for only when the business can keep up with the obligations.
Self Assessment, records and payment statements
Sole traders and partners normally report the full invoice value in their Self Assessment return and enter the deductions contractors made. HMRC uses the deductions as credit against the final tax and National Insurance calculation, which may leave further tax to pay or produce a refund.
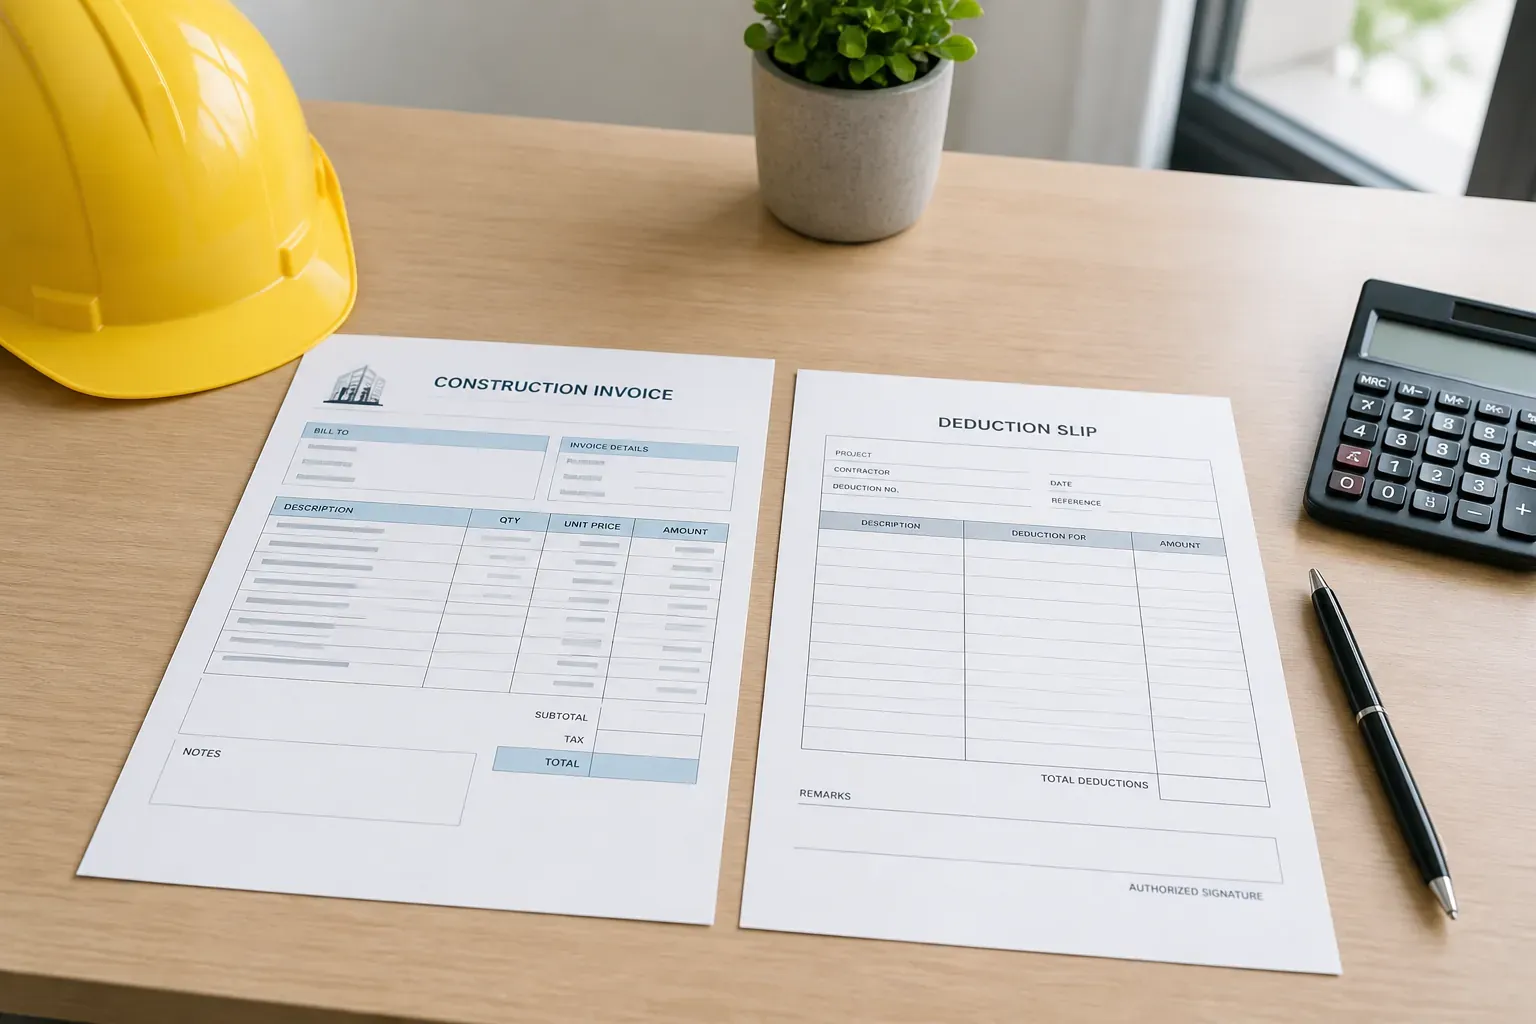
Where deductions are made, contractors must provide a payment and deduction statement at least monthly, within 14 days of the end of the tax month. Keep every statement with invoices, receipts and supporting accounting records. It is essential evidence of tax already paid to HMRC.
For a limited-company subcontractor, CIS deductions are generally recovered through the company's payroll process, rather than by deducting them from the Corporation Tax return. That route is technical, so get advice before making a claim.
Keep control of the administration
CIS often overlaps with VAT, PAYE, Self Assessment, cash flow and payroll. A routine that verifies subcontractors, files statements and stores material evidence each month is far easier to manage than a year-end reconstruction.
Common questions
Why might a subcontractor have 20% or 30% deducted?
The normal rate for a registered and verified subcontractor is 20%. A 30% higher rate can apply if they are not registered, cannot be verified or give incorrect details. Gross payment status means no CIS deduction is made.
Do CIS deductions settle my tax bill?
No. They are advance payments. Sole traders and partners normally report the full invoiced income and CIS deductions in Self Assessment, then HMRC calculates the final position.
Related guidance
Continue with another useful guide from this topic.
Tax & deadlines
Making Tax Digital for Income Tax: are you ready for the HMRC changes?
A full guide to MTD for Income Tax, qualifying income, digital record keeping, quarterly updates and the dates that matter.
Tax & deadlines
Self Assessment: who needs to file a 2025/26 tax return?
Find out who may need to file a 2025/26 Self Assessment return, the key dates and the records to prepare.
Tax & deadlines
VAT in the UK: what business owners need to know
Learn when VAT registration is required, how the £90,000 threshold works, and what to record, charge and reclaim.
Need tailored support?
Talk through your position with Sparks
Bring your questions and records to a free consultation. We will explain the next steps in clear, practical terms.