
What Legal and Tax Obligations Does a UK Limited Company Have?
A clear guide to the main Companies House and HMRC responsibilities for UK limited company directors.
AI-assisted official-source check · 7 September 2026 — Company-register changes effective from 18 November 2025.
In brief
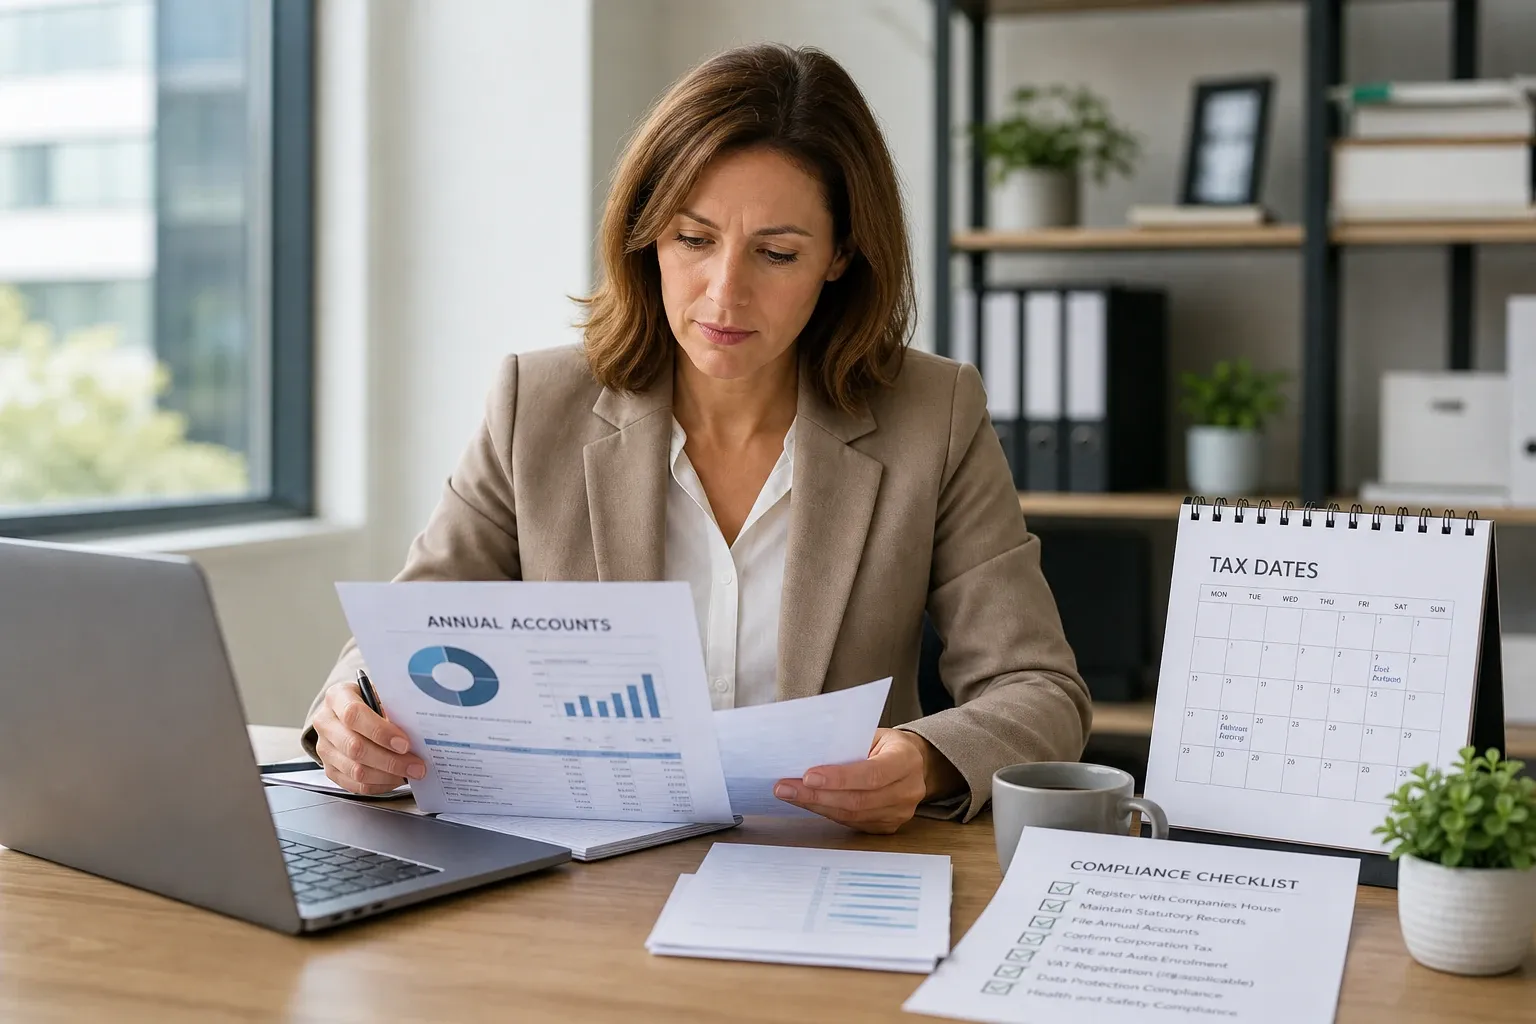
A UK limited company normally keeps proper accounting records, files annual accounts and a confirmation statement with Companies House, files a Company Tax Return with HMRC and pays Corporation Tax where due. VAT, payroll, CIS, pensions and other rules may also apply.
Companies House and HMRC are different
Companies House maintains the public company register, including the registered office, directors, shareholders, people with significant control, annual accounts and confirmation statements. HMRC manages tax, including Corporation Tax, VAT and PAYE.
Filing annual accounts with Companies House does not complete the Company Tax Return due to HMRC. The filings are related, but they are separate obligations with different deadlines.
Keep company and accounting records
The company must keep records that explain its transactions and financial position: invoices, receipts, bank statements, sales, purchases, payroll, VAT records, assets and liabilities. It must also maintain its register of members and other required company records. Separate local registers of directors, secretaries and PSCs ceased to be required on 18 November 2025, but their details must still be kept current at Companies House.
Regular records help directors understand profit, cash flow, tax and how much money can safely be withdrawn. The company’s money does not belong personally to the director.
File annual accounts
Most companies file annual accounts with Companies House. First accounts commonly have a different deadline from later accounts. A private company’s first accounts are usually due 21 months after incorporation, while later accounts are usually due 9 months after its financial year end.
Late accounts can trigger automatic penalties. Repeated failure can lead to more serious enforcement, so the exact deadline should be placed on the company calendar.
File the Company Tax Return
The Company Tax Return, often called the CT600, reports taxable profit and the Corporation Tax position to HMRC. It is separate from Companies House accounts, although the accounts and tax computation support it. The return is normally due 12 months after the accounting period ends.
Pay Corporation Tax
For most small companies, Corporation Tax is normally due 9 months and 1 day after the accounting period ends. The payment deadline therefore usually arrives before the CT600 filing deadline. Set money aside during the year rather than waiting for the final accounts.
File the confirmation statement
A confirmation statement verifies key information on the Companies House register, including directors, registered office, shareholders, PSCs and SIC codes. It must be filed at least every 12 months even where nothing has changed.
Changes that must be reported sooner should not be held back until the next confirmation statement. Keep the registered office, directors, PSCs, share information and other statutory details current.
Check VAT and payroll
VAT registration depends on taxable turnover and the other registration rules. Turnover is measured on a rolling 12-month basis, not simply by accounting year, and a forward-looking test can also trigger registration.
PAYE payroll may be required when the company pays salaries to directors or employees. Payroll can also involve National Insurance, pensions and benefits. Salary and dividends are different and must be properly documented.
Other obligations may apply
Depending on its work, the company may also have CIS, workplace pension, data protection, licensing or industry-specific obligations. A dormant company still normally has Companies House filings even though its tax position may be simpler.
Common compliance mistakes
- Treating annual accounts and the Company Tax Return as the same filing.
- Forgetting that Corporation Tax is normally payable before the CT600 is due.
- Missing the confirmation statement because nothing changed.
- Using company money informally without recording salary, dividends, expenses or director’s loans.
- Checking VAT only at the company year end instead of monitoring rolling turnover.
Build a compliance calendar
- Record the annual accounts deadline.
- Record the Corporation Tax payment deadline.
- Record the Company Tax Return deadline.
- Schedule the confirmation statement review.
- Add VAT return and payment dates where registered.
- Add payroll and pension dates where applicable.
- Update company records often enough to support every deadline.
Common questions
Does a dormant company still need to file accounts?
Yes. Dormant companies normally retain Companies House filing responsibilities, although their filings may be simpler.
Is the confirmation statement the same as annual accounts?
No. Annual accounts report financial information; the confirmation statement verifies information held on the public company register.
Can an accountant take responsibility for everything?
An accountant can prepare and file information, but the directors remain legally responsible for the company and its records.
Do all limited companies need VAT?
No. VAT registration depends on taxable turnover, the forward-looking test and any decision to register voluntarily.
Related guidance
Continue with another useful guide from this topic.
Companies & compliance
Companies House Changes: What Directors Need to Know
Key Companies House reforms affecting directors, PSCs, company filings and identity verification.
Companies & compliance
When Are Limited Company Accounts Due?
Understand Companies House accounts deadlines, first accounts and how accounts differ from Corporation Tax returns.
Companies & compliance
What Is a Confirmation Statement and When Is It Due?
Understand what a confirmation statement is, what it confirms and when UK companies need to file it.
Need tailored support?
Talk through your position with Sparks
Bring your questions and records to a free consultation. We will explain the next steps in clear, practical terms.