
How to Set Up a Limited Company in the UK
Learn the practical steps to register a UK limited company and set it up correctly for tax, records and future growth.
AI-assisted official-source check · 7 September 2026 — Director identity verification at incorporation.
In brief
To set up a UK limited company, choose the name, directors, shareholders, PSCs, registered office and SIC code, then incorporate it with Companies House. After registration, set up Corporation Tax and business banking, maintain company records and check whether VAT, payroll, CIS or other obligations apply.
Who this guide is for
This guide is for business owners who want to start trading through a UK limited company, including sole traders moving into a company structure, contractors, consultants and new entrepreneurs. If you are not sure whether a company is the right structure, compare it with operating as a sole trader before registering.
What a limited company is
A limited company is legally separate from the people who own and run it. It can own assets, enter contracts, make profits and pay tax in its own name. Directors run the company and shareholders own it. In many small companies, the same person is both director and shareholder.
Limited liability and a formal structure can be useful, but a company also brings Companies House filings, Corporation Tax, accounting records and public company information. Registration is therefore the beginning of the setup process, not the end.
1. Choose the structure and company name
Start by deciding why a company suits the business. Consider commercial risk, the money you need personally, expected profit, client requirements and the additional administration. A company is not automatically better for every small business.
The company name must follow Companies House rules. It cannot be the same as an existing registered name, and some words need approval. Also check domain names, social handles and trade marks before committing to a name that will be difficult to change later.
2. Appoint directors, shareholders and PSCs
A private company limited by shares needs at least one director and one shareholder; the same person can be both. Directors are responsible for running the company and ensuring that its legal and tax obligations are met. Hiring an accountant does not remove that legal responsibility. Since 18 November 2025, directors must verify their identity and provide their Companies House personal codes when incorporating. Check the separate identity-verification deadlines for PSCs as well. Since 18 November 2025, directors must verify their identity and provide their Companies House personal codes when incorporating. Check the separate identity-verification deadlines for PSCs as well.
You must also identify people with significant control, usually people who hold more than 25% of the shares or voting rights or otherwise exercise significant influence. Share rights and ownership should be considered carefully where there is more than one owner.
3. Select the official addresses and SIC code
The company needs a registered office address for statutory correspondence and an appropriate registered email address that is monitored. The registered office appears on the public register, so consider a professional address service if you do not want to use a home address.
Choose a SIC code that accurately describes the company’s real activity. It can be updated later, but a sensible code from the start helps keep the public record accurate.
4. Prepare the company documents
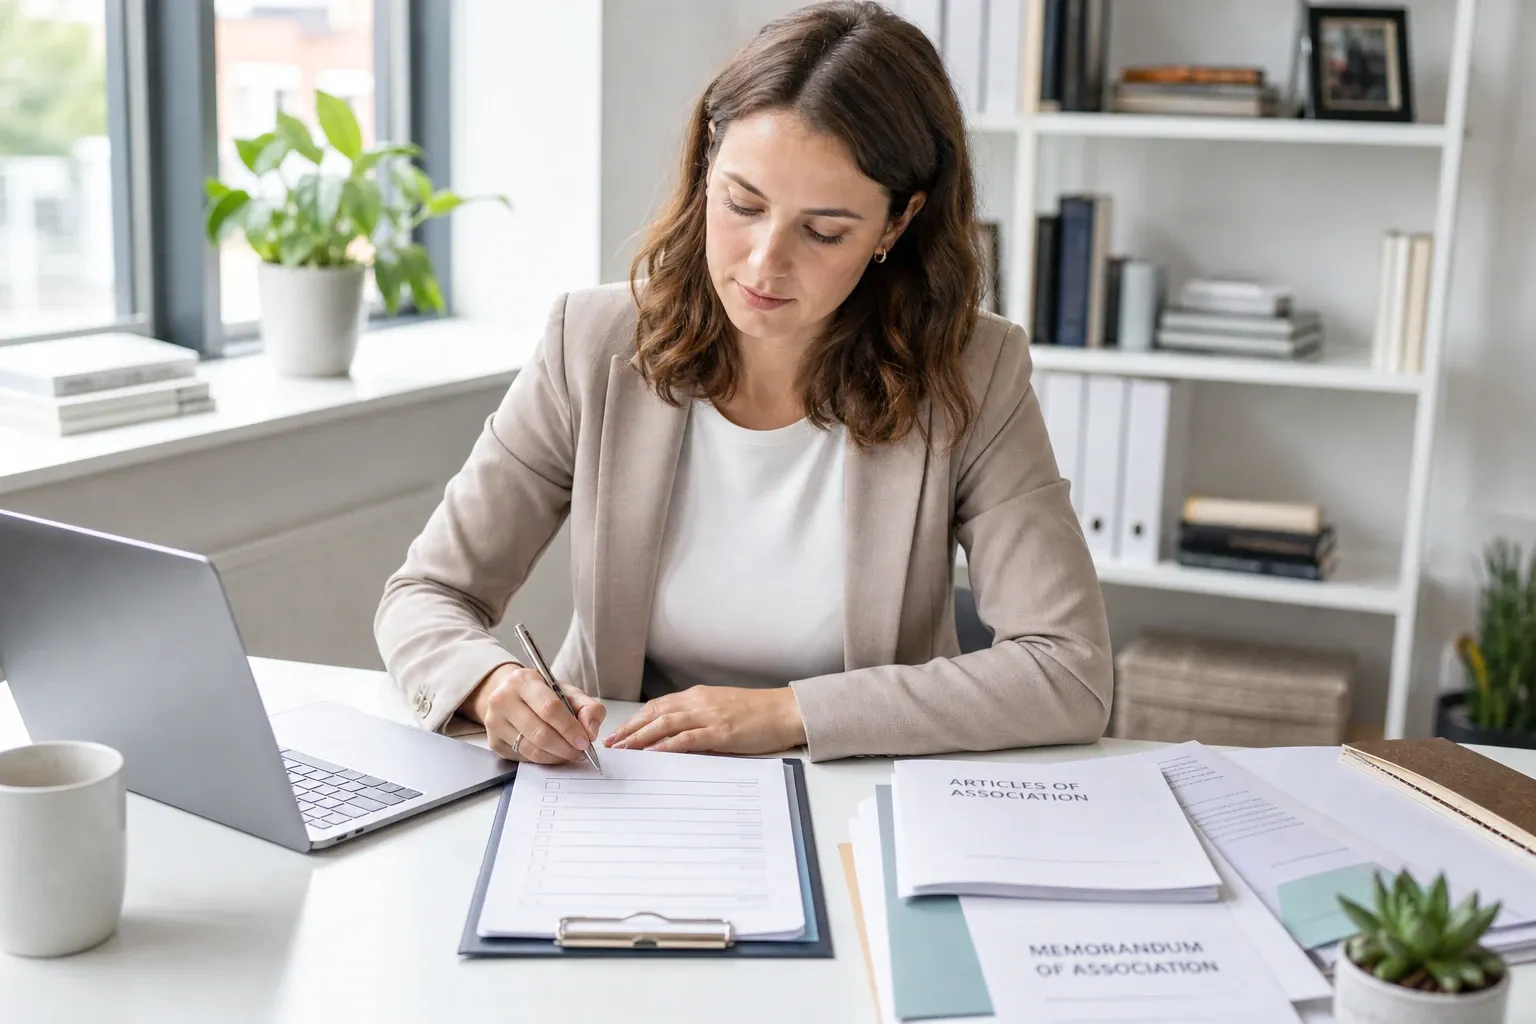
A company needs constitutional documents, including a memorandum and articles of association. Model articles work for many small companies, but businesses with several shareholders, unusual ownership or special decision-making rules should check whether tailored documents or legal advice are needed.
5. Register with Companies House
Once the details are ready, register the company with Companies House. Incorporation creates the legal entity and gives it a company number. A company can remain dormant before trading, but dormant companies still have filing responsibilities.
6. Set up Corporation Tax
HMRC normally sends company tax information after incorporation. Directors must still make sure the company is registered correctly for Corporation Tax, understand its accounting period and tell HMRC when it starts doing business.
For most small companies, Corporation Tax is normally due 9 months and 1 day after the end of the accounting period. The Company Tax Return normally has a later deadline, so both dates need to be recorded separately.
7. Open a company bank account
A company should have its own bank account because company money is legally separate from the director’s personal money. Separate banking makes transaction records and supporting evidence clearer and reduces the risk of personal spending being treated incorrectly.
8. Start keeping company records immediately
Keep records of sales, expenses, invoices, receipts, bank transactions, assets, payroll, VAT and money taken by directors from the first day. Waiting until the year end increases the risk of lost evidence, inaccurate tax and poor cash-flow decisions.
9. Check VAT, payroll and other registrations
Not every new company needs VAT or PAYE immediately, but every company should check. VAT registration can be compulsory when taxable turnover exceeds the threshold or is expected to exceed it under the forward-looking test. Payroll may be needed when salaries are paid to directors or employees. CIS, pensions or industry rules may also apply.
Common setup mistakes
- Treating Companies House incorporation as if it also completed Corporation Tax, VAT and payroll setup.
- Using a personal bank account for company transactions.
- Choosing the name, SIC code or share structure without enough thought.
- Taking company money without recording whether it is salary, dividend, expense repayment or a director’s loan.
- Leaving company records until the first filing deadline.
Your setup checklist
- Confirm that a limited company suits the business.
- Choose and check the company name.
- Confirm directors, shareholders and PSCs.
- Select the registered office and email address.
- Choose the SIC code and company documents.
- Register with Companies House.
- Plan Corporation Tax, business banking and your own record system.
- Check VAT, payroll, CIS and other obligations.
Common questions
Can one person set up a limited company?
Yes. A private limited company can have one director and one shareholder, and the same person can hold both roles.
Do I need an accountant to register a company?
You can register it yourself, but an accountant can help you choose an appropriate setup and plan the tax, banking, record requirements and filing work that follows incorporation.
Can I register a company and not trade yet?
Yes. A company can be dormant before it trades, but dormant companies still normally have Companies House filing responsibilities.
Is a limited company the same as being self-employed?
No. A limited company is a separate legal entity. A sole trader is self-employed and trades personally.
Related guidance
Continue with another useful guide from this topic.
Companies & business structure
Can One Person Own and Run a Limited Company?
How a one-person UK limited company works and what responsibilities still apply.
Companies & business structure
Sole Trader vs Limited Company: Which Is Better?
Compare tax, administration, liability and growth considerations before choosing a structure for your UK business.
Companies & business structure
Corporation Tax in the UK: a guide for limited company directors
A clear guide to Corporation Tax rates, taxable profit, payment dates, the CT600 and company record keeping.
Companies & business structure
Sole trader or limited company in 2026?
Compare tax, administration, liability and growth considerations before choosing the right structure for your business.
Need tailored support?
Talk through your position with Sparks
Bring your questions and records to a free consultation. We will explain the next steps in clear, practical terms.